Not every high-net-worth buyer in Las Vegas is relocating here. A growing share are doing something more specific: making Las Vegas one stop in a rotation of homes, chosen deliberately for what it does for their tax picture and their calendar — not as a full-time address.
The Math Behind the Decision
Nevada’s combination of no state income tax, no estate tax, and no inheritance tax is the foundation of this trend, and the numbers are large enough to justify a dedicated property even for buyers who are only here part of the year. A retired couple relocating from California with $1.2 million in annual income can save somewhere in the range of $84,000 to $120,000 a year in state taxes alone. At the luxury-property-owner level — $2 million or more in income — that savings climbs to roughly $200,000 to $400,000 annually. For a buyer managing wealth across multiple states, establishing genuine Nevada residency while maintaining a second home in California, New York, or Washington isn’t a lifestyle preference; it’s a financial strategy with a seven-figure impact over time.
Built for Being Empty
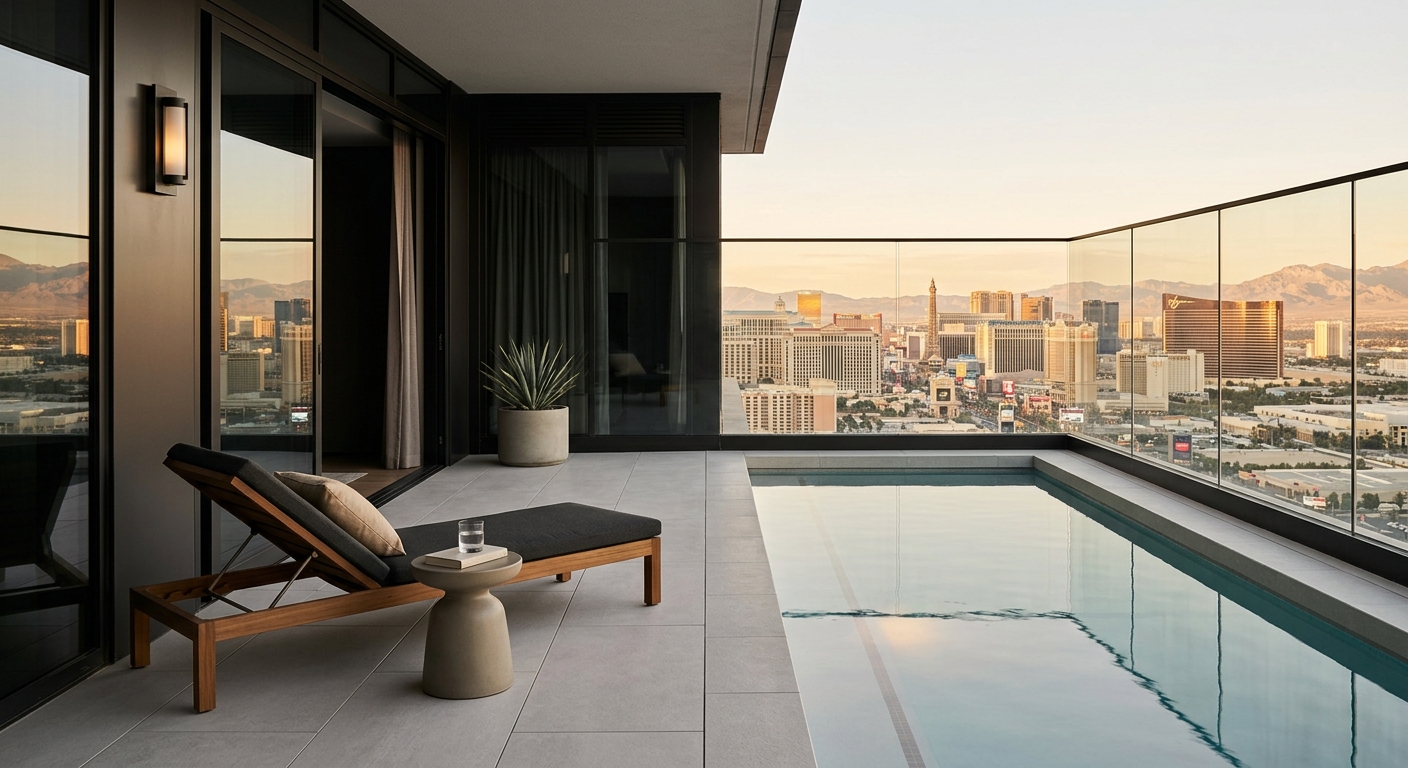
What makes Las Vegas specifically suited to this model, more than other low-tax states, is that the valley’s luxury housing stock is largely designed for it. A huge share of new guard-gated and resort-style communities are purpose-built around lock-and-leave living — HOA-managed landscaping, resort amenities that don’t require a homeowner’s daily attention, and security infrastructure that works whether the owner is in residence or not. A four-hour drive from the Bay Area buys a resort-style backyard in a community engineered to sit empty for weeks at a stretch without anyone noticing.
Not Just Retirees Anymore
The classic version of this buyer was a retiree splitting time between a primary home and a Nevada property purely for the tax benefit. The 2026 version looks different: it’s increasingly a working couple, often from the Bay Area or Seattle, who’ve realized the math works even while they’re still earning actively, not just after they stop. Recent migration patterns out of high-tax West Coast markets specifically point to Las Vegas, Austin, and Nashville as the destinations absorbing this wealth, with Las Vegas standing out for proximity to California and the breadth of resort-style inventory built to support part-time occupancy.
The Financing Wrinkle Worth Knowing
One detail that catches second-home buyers off guard: lenders price these purchases differently depending on intent. A genuine second home — one you’ll occupy part-time and aren’t relying on for rental income to qualify — can often close with around 10% down at rates close to primary-residence pricing. The moment rental income becomes part of the qualification story, the loan moves into investment-property territory, with different down payment requirements and rates. If tax strategy is the goal, structuring the purchase and the financing correctly from the start matters as much as the property itself.
What I Walk Clients Through
For buyers considering this path, the property search is really the last step. Before we tour anything, I want to know how many months a year they’ll realistically be here, whether residency will be formally established in Nevada or just a part-time home maintained alongside a primary residence elsewhere, and how they want the purchase financed. Those answers shape everything from which communities make sense to how the offer gets structured — and they’re worth sorting out with a tax advisor before, not after, you find the house.
If a Nevada second home is part of your broader financial picture, let’s talk through the structure before you start touring — it’ll save you from falling for a property that doesn’t actually fit the plan.